Learn what travel insurance for Japan covers, what it doesn’t, and how to choose the best policy for a seamless, worry-free trip.
Travel insurance for Japan is worth understanding before you buy it: what a policy covers, what it doesn't, and how to pick one that fits your trip.
Japan is a safe country, but medical care is expensive for visitors and natural disasters do happen. This guide covers whether you need insurance, which coverage matters, and the expensive mistakes to avoid.
Do You Need Travel Insurance for Japan?
No. Japan does not legally require travel insurance to enter the country in 2025.
Tourist visas don't come with an insurance requirement. During the COVID-19 pandemic Japan briefly made visitors carry medical coverage for the virus, but that rule ended when travel restrictions lifted.
Going without insurance is still a real financial risk. Medical care costs far more than in many Western countries, and most hospitals make foreign tourists pay up front.
What You're Actually Protecting Against
Medical Costs Without Insurance
Japanese healthcare is excellent, and it's expensive if you're a visitor without coverage.
| Medical Scenario | Cost Range (Yen) | Cost Range (USD) |
|---|---|---|
| Emergency room visit | ¥10,000-30,000 | $70-210 |
| ER visit (complex cases) | Up to ¥50,000 | Up to $350 |
| Broken bone (simple fracture) | ¥30,000-80,000 | $210-560 |
| Broken bone (surgery required) | ¥200,000-400,000 | $1,400-2,800 |
| Food poisoning (2-day hospitalization) | ¥150,000-300,000 | $1,050-2,100 |
| Appendicitis surgery (3-day stay) | ¥400,000-600,000 | $2,700-4,200 |
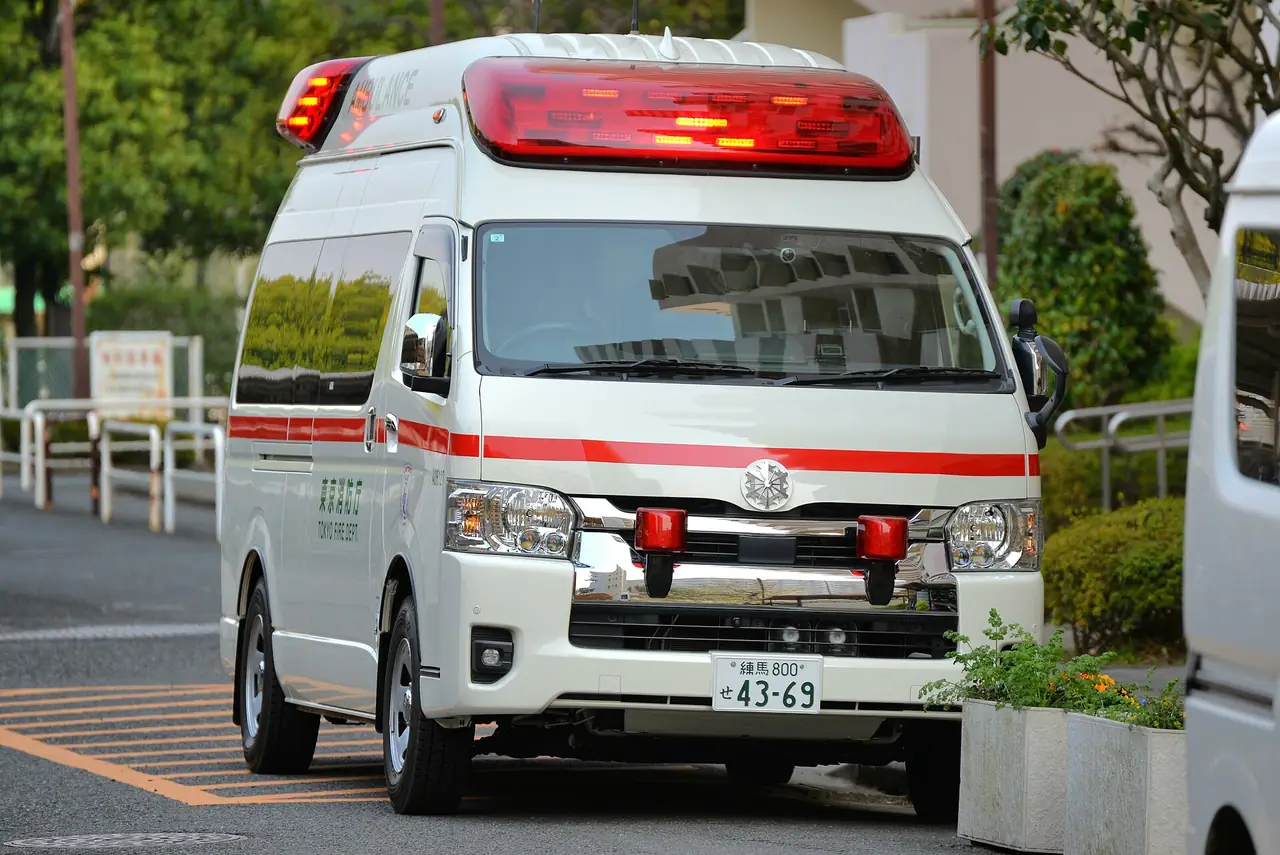
Most hospitals (70-80%) ask foreign tourists for payment or a deposit up front. Only the big international hospitals bill insurers directly.
Natural Disaster Trip Disruptions
| Disaster Type | Frequency/Impact | Typical Impact on Travel |
|---|---|---|
| Typhoons | 3-5 per season affecting air travel | 2-4 days airport disruptions (Aug-Sep peak) |
| Typhoon delays | Most storms | 12 hours to 3 days (most resolve in 24-48 hrs) |
| Severe typhoons | Occasional | 3+ day backlogs due to aircraft repositioning |
| Earthquakes | Frequent | Rarely disrupt travel significantly; large quakes may affect trains/accommodations temporarily |
In a typical year, 3-5 typhoons per season disrupt air travel in Japan.
Medical Evacuation Costs
| Evacuation Type | Cost Range | When Needed |
|---|---|---|
| Domestic (rural to Tokyo) | $10,000-50,000 | Ground ambulance + helicopter if required |
| International repatriation | $50,000-150,000+ | Evacuation to home country for treatment |
First-time visitors make the same kind of trade-off when it comes to Tokyo's transit system, food safety, and cultural norms without local knowledge: at each decision, how much risk is worth avoiding, and at what cost.
Quick Recommendations by Traveler Profile
| If You're... | Priority Coverage | Key Considerations |
|---|---|---|
| Family with kids | Medical (¥100K+), trip interruption | Kids get sick unexpectedly. Pediatric care in Japan is excellent but expensive. Trip interruption covers illness-related itinerary changes. |
| Senior traveler (65+) | Medical (¥250K+), evacuation (¥500K+) | Age increases medical premiums 2-3x but also increases likelihood of needing coverage. Evacuation from rural areas to Tokyo can exceed $50,000. |
| Adventure traveler (skiing, hiking) | Adventure sports rider, evacuation | Standard policies exclude skiing and remote hiking. Niseko to Sapporo medical evacuation alone can cost $50,000+. |
| Budget backpacker | Basic medical, skip extras | If your trip costs under $1,000 and you're healthy, minimal coverage may suffice. Premium might exceed likely claims. |
| Business traveler (short trip) | Check credit card first | Premium cards often cover short trips adequately. Verify limits before buying duplicate coverage. |
| Pre-existing conditions | Buy within 14 days of deposit | Waiver window closes quickly. After that, conditions are permanently excluded. |
Coverage Types That Matter for Japan
In Japan, expensive hospitals and typhoon delays decide what you need. Everything else is optional.
| Coverage Type | Priority for Japan | Why It Matters | Cost Impact |
|---|---|---|---|
| Medical expenses | Essential | High costs + upfront payment requirements | Base coverage |
| Emergency evacuation | Essential | Remote area access + repatriation costs | Included in most |
| Trip cancellation/interruption | Essential | Non-refundable costs protection | Standard feature |
| Trip delay | Important | Typhoon season disruptions common | Standard feature |
| Lost/stolen luggage | Important | Low theft rates, but standard coverage | Standard feature |
| Cancel for any reason (CFAR) | Optional | Flexibility for non-covered reasons | +40-50% cost |
| Adventure sports riders | Optional* | Required only if skiing, diving, etc. | +15-30% cost |
*Becomes essential if engaging in excluded activities.
How Coverage Levels Map to Japan Costs
A policy with a low limit can leave you paying most of a serious hospital bill yourself.
Is $50,000 Medical Coverage Enough?
$50,000 pays for routine treatment and minor surgery. It may not stretch to major surgery if there are complications.
Major surgery runs $30,000-80,000+ depending on how complex it is, and an ICU stay adds $5,000-10,000 a day.
It's an acceptable minimum for a short trip with low-risk plans. For a longer stay, or if you have health concerns, it isn't enough.
Is $250,000 Medical Coverage Enough?
$250,000 covers most medical situations in Japan, including major surgery, complications, and a long hospital stay.
It handles serious emergencies, up to the point of extended critical care or an international medical evacuation.
This is the level we'd suggest for most travelers. You get solid protection without paying top-tier premiums.
Mapping Scenarios to Required Coverage
| Scenario | Estimated Cost | Minimum Coverage |
|---|---|---|
| Simple fracture (casting, follow-up) | ¥30,000-80,000 ($210-560) | $50,000 medical |
| Appendicitis surgery with 3-day stay | ¥400,000-600,000 ($2,700-4,200) | $50,000 sufficient, $100,000+ preferred |
| Major surgery with ICU complications | $50,000-100,000+ | $250,000 medical |
| Medical evacuation from rural area to Tokyo | $10,000-50,000 | $100,000 evacuation |
| International medical repatriation | $50,000-150,000+ | $250,000-500,000 evacuation |
Provider Comparison: Coverage Tiers
Insurers sell coverage in tiers. Knowing what each tier usually includes keeps you from overpaying or buying too little.
| Coverage Type | Budget Tier | Standard Tier | Comprehensive Tier |
|---|---|---|---|
| Medical coverage | $25,000-75,000 | $100,000-250,000 | $500,000-1,000,000+ |
| Trip cancellation | 50-75% of trip cost | 100% of trip cost | 100% + cancel-for-any-reason |
| Emergency evacuation | Excluded or $25,000 | $250,000-500,000 | $1,000,000+ |
| Luggage coverage | Basic or excluded | $1,000-2,500 | Enhanced coverage |
| Adventure sports | Excluded | Add-on available | Often included |
| Cost (1 week, age 30-40) | Varies | $40-80 | Premium pricing |
Budget Tier
Best for very short trips, travelers with few health risks, and people whose credit card coverage fills in the gaps.
It won't cover a major medical emergency or an evacuation.
Standard Tier
This is the right tier for most people visiting Japan, with broad coverage at a reasonable price.
It usually includes trip delay for natural disasters, which matters in typhoon season.
Comprehensive Tier
Best for travelers with significant health concerns, expensive trips, or adventure activities planned.
It may add concierge services, automatic adventure sports coverage, and higher luggage limits.
Common Exclusions & What They Mean in Japan
Every standard policy excludes certain situations. If you know the exclusions, you won't get a claim denied by surprise.
| Exclusion Type | What's Excluded | How to Get Coverage | Japan-Specific Impact |
|---|---|---|---|
| Pre-existing conditions | Conditions diagnosed/treated before purchase | Buy within 10-21 days of trip deposit | High medical costs make this critical |
| Adventure sports | Skiing, diving, remote hiking | Purchase adventure sports rider (+15-30%) | Remote ski resorts = expensive evacuations |
| Mental health | Psychological treatment, crises | Varies by provider | Check policy details carefully |
| Drugs/alcohol | Injuries while intoxicated | Not available | Japan's strict drug laws compound issues |
| Advisory areas | Travel to warned regions | Not available while advisory active | Coverage void if you travel anyway |
Pre-Existing Medical Conditions
Most policies won't cover a condition that was diagnosed or treated before you bought the policy.
There's a waiver window. Buy within 10-21 days (usually 14 days) of your first trip deposit and pre-existing conditions are covered. Miss it, and they stay excluded.
If you manage diabetes, a heart condition, or another ongoing health issue, that waiver matters a great deal. With Japan's medical costs, an excluded condition can be financially ruinous.
If you're an older traveler or have mobility needs, insurance is only one part of accessible travel planning in Tokyo. Even the most tourist-friendly parts of the city take careful route planning.
Adventure and Extreme Sports
Standard policies exclude skiing, scuba diving, remote hiking, and similar activities.
If you're skiing in Hokkaido or climbing Mt. Fuji, buy the adventure sports rider.
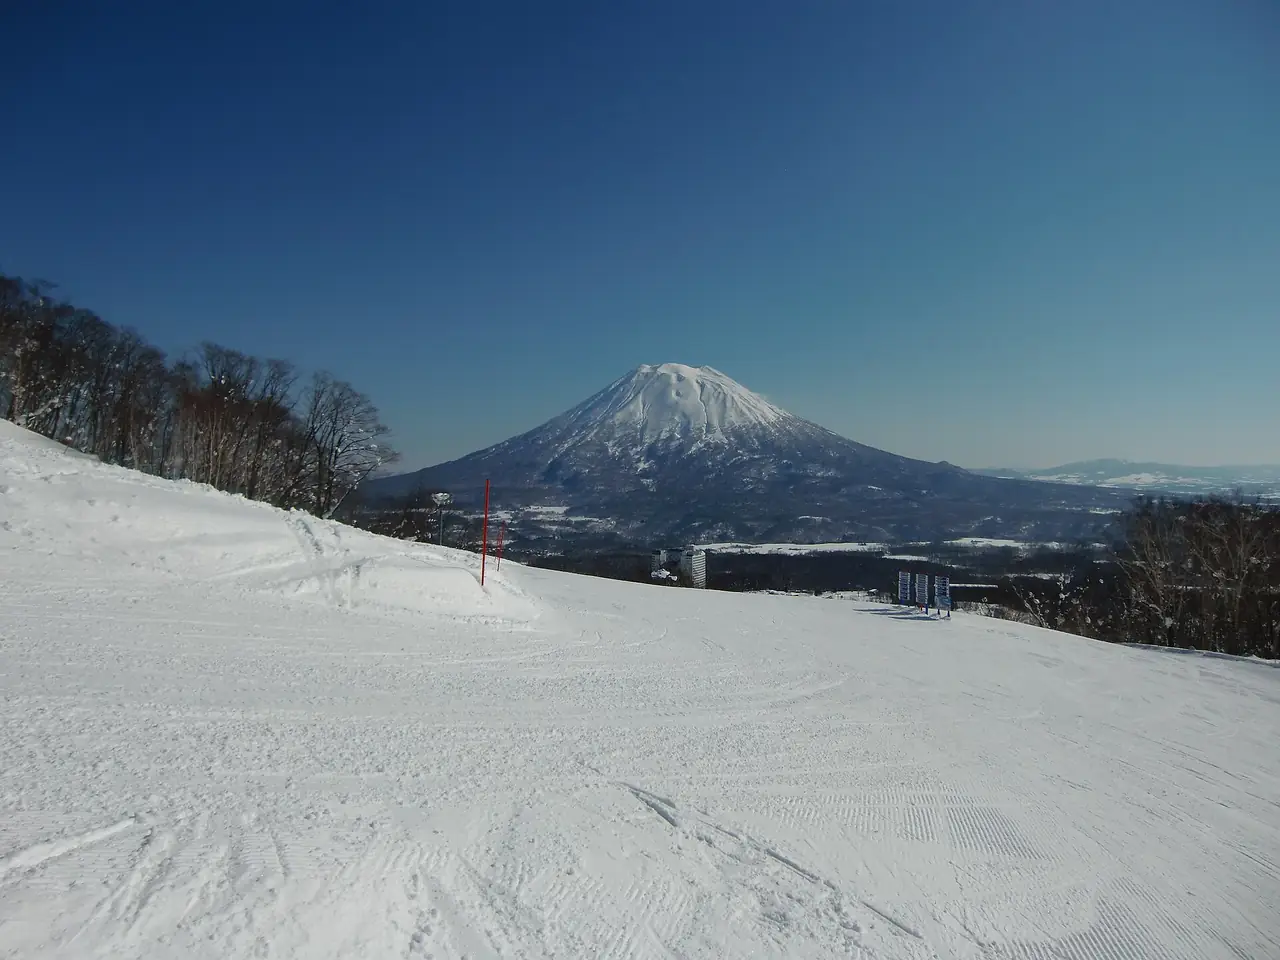
Ski resorts here are remote. Evacuation from Niseko to Sapporo, and possibly on to Tokyo, can cost more than $50,000.
Mental Health and Elective Procedures
Policies usually exclude psychological treatment, mental health crises, and elective procedures.
Coverage for emergency mental health treatment depends on the provider, so read your policy.
Injuries Due to Drugs or Alcohol
Injuries that happen while you're drunk or under the influence aren't covered.
Japan's drug laws are extremely strict, so any drug-related incident is a legal problem as well as an insurance one.
Travel to Advisory Areas
If your government issues a travel advisory for a region and you go anyway, your coverage there may be void.
Buying & Using Insurance in Japan
Where to Buy
| Purchase Method | Advantages | Disadvantages |
|---|---|---|
| Direct from providers online | Simplest option, easy comparison | Must research options yourself |
| Through travel agents | Expert explanation of nuances | Limited provider selection |
| Credit card benefits | Already included, no extra cost | Severe limitations, gaps in coverage |
Credit Card Coverage Limitations
People often assume their credit card has them covered. The usual limits:
| Coverage Area | Typical Credit Card Limit | Limitation |
|---|---|---|
| Medical coverage | $0-50,000 | Many cards exclude medical entirely |
| Trip cancellation | Trip cost charged to card | Must charge entire trip to that specific card |
| Pre-existing conditions | Excluded | Almost universal exclusion |
| Adventure sports | Excluded | No coverage for skiing, diving, etc. |
| Age limits | 65-70 maximum | Older travelers often excluded |
| Coverage type | Secondary | Requires filing with another policy first |
Premium cards do better, but even they rarely match a dedicated travel policy on medical cover.
When to Buy
| Coverage Goal | Purchase Timing | Reason |
|---|---|---|
| Pre-existing condition coverage | Within 10-21 days of first trip deposit | Waiver window closes after this period |
| Trip cancellation | Before any non-refundable bookings | Can't cancel what's already paid |
| Medical coverage | Before departure | Some allow post-arrival but limited benefits |
| Full protection | As early as possible | Lower premiums, maximum coverage options |
Leave it until a week before you fly and you'll pay higher premiums and lose the pre-existing condition waiver.
What to Carry
-
Insurance certificate (digital and printed)
-
Policy number
-
Emergency contact numbers (local and international)
-
List of covered and excluded activities
Using Insurance at Hospitals
Most Japanese hospitals want payment or a deposit up front, and few bill international insurers directly.
What usually happens:
-
Receive treatment
-
Pay hospital bill upfront (credit card typically accepted at international hospitals)
-
Collect itemized receipts, discharge summary, and diagnosis documentation
-
File claim with insurer
-
Wait 2-6 weeks for reimbursement (straightforward claims with complete documentation)
The exception is the big international hospitals in Tokyo and other large cities, some of which have direct billing arrangements with major insurers. If you can, call your insurer before you get treated.
Required Documentation for Claims
-
Original itemized receipts from hospital/clinic
-
Medical discharge summary or doctor's report
-
Diagnosis codes (ICD codes if available)
-
Proof of payment
-
Completed claim form from insurer
-
Copy of passport and policy documents
-
Police report (if injury from accident or crime)
If anything is missing, expect your claim to take another 4-6 weeks.
English-Speaking Hospital Access
Hospitals in the major cities have English-speaking staff, but full English service is limited to the international hospitals.
Tokyo
| Hospital Name | Specialties | Payment Notes |
|---|---|---|
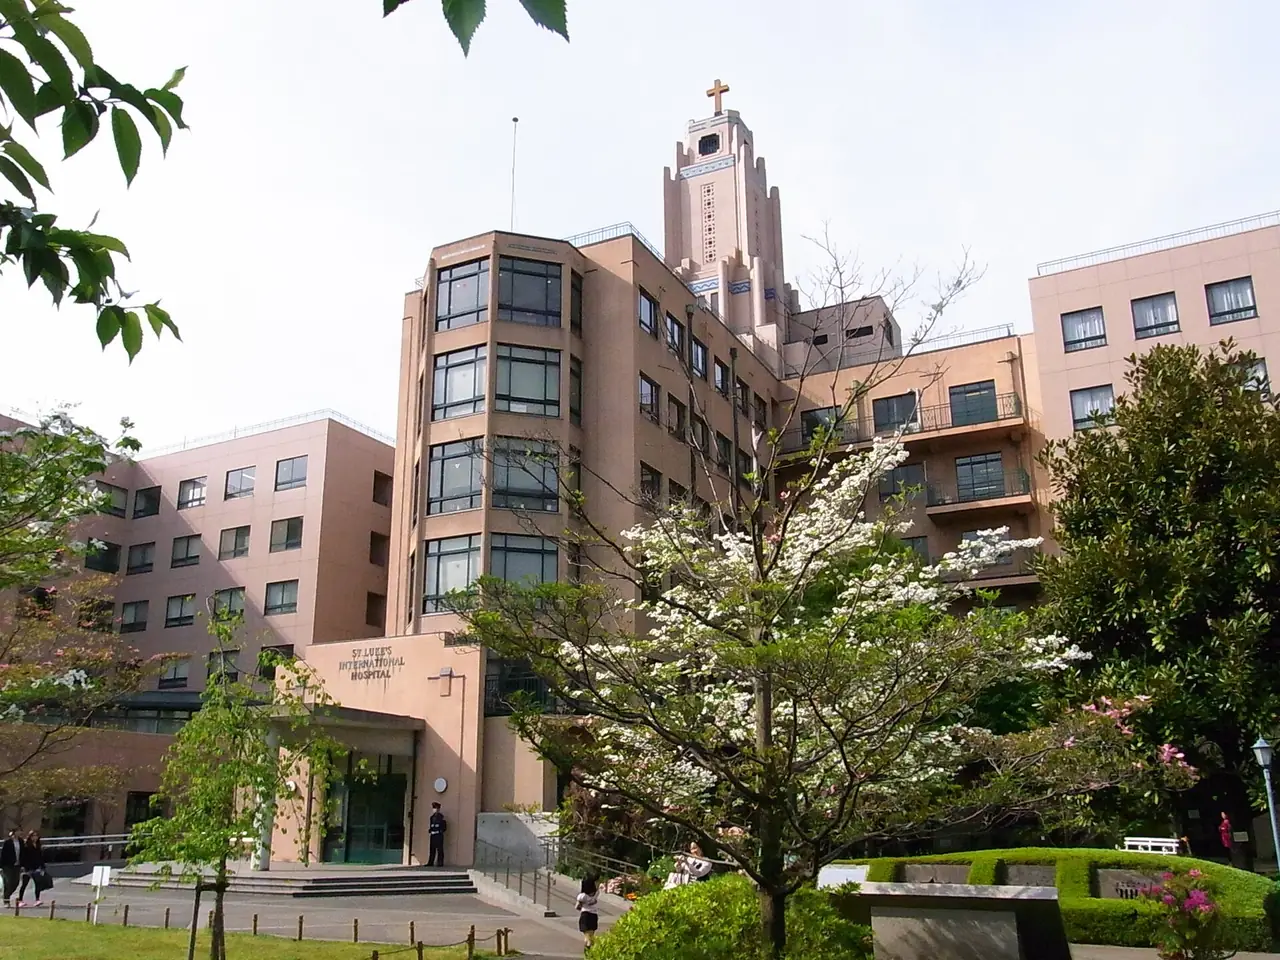
| St. Luke's International Hospital | Full-service, all specialties | International services, some insurer direct billing |
| Tokyo Medical and Surgical Clinic | Primary care, general practice | English-speaking staff, credit cards accepted |
| The University of Tokyo Hospital | Full-service, global care unit | Large university hospital, limited English |
Osaka
| Hospital Name | Specialties | Payment Notes |
|---|---|---|
| Osaka Red Cross Hospital | General and emergency care | Some English support |
| Osaka International Cancer Institute | Specialized cancer care | International patient support |
Kyoto
| Hospital Name | Specialties | Payment Notes |
|---|---|---|
| Kyoto University Hospital | Full-service, some English | Large hospital, variable English availability |
Other Major Cities
| City | Hospital Name | Notes |
|---|---|---|
| Yokohama | Yokohama City Minato Red Cross Hospital | Foreigner assistance available |
| Fukuoka | Fukuoka Sanno Hospital | English-speaking staff, modern facilities |
| Sapporo | Sapporo Medical University Hospital | International desk available |
Realistic Expectations
Most hospitals have someone who speaks English. Full English service, though, is mostly found at the major international hospitals in Tokyo and Osaka.
In smaller cities and the countryside, English support is thin. A hospital may offer translation or let you use an interpreter app, but expect some difficulty communicating.
Look up your insurer's preferred hospitals before you leave. Some insurers work with particular facilities, which makes direct billing easier.
Even where staff speak English, dealing with Japanese healthcare in an emergency is a lot to handle. Many travelers find that a local guide who knows Tokyo's healthcare system gives them peace of mind that insurance alone doesn't, especially families and people with mobility needs.
When You Might Not Need Insurance
In some situations the coverage is redundant or costs more than it's worth.
| Scenario | Requirements | Verify Before Skipping | Risk Level |
|---|---|---|---|
| Strong credit card coverage (short trip) | Medical >$50K, trip cancellation matches cost, primary coverage, no age limits | Read card benefits document carefully | Low (if all requirements met) |
| Long-term Japan residents | Japanese health insurance (shakai/kokumin hoken) | May still need trip cancellation coverage | Low for medical, varies for trip costs |
| Very low trip costs | Total trip under $500, healthy, no pre-existing conditions, refundable bookings | Premium may exceed financial risk | Low (premium cost vs. exposure) |
| Self-insurance capacity | Can absorb $10,000-20,000 medical bill, not engaging in high-risk activities | Only for travelers with substantial liquid savings | Medium (acceptable for small % of travelers) |
Most credit cards exclude medical coverage or cap it low. Check exactly what yours covers before you decide to go without.
Cost-Benefit Examples
| Traveler Profile | Insurance Recommendation |
|---|---|
| Day trip from cruise ship | Unnecessary |
| 3-day business trip, age 30, excellent credit card coverage | Optional |
| 2-week family vacation, age 40, with kids | Strongly recommended |
| Ski trip to Hokkaido, any age | Essential (with adventure sports coverage) |
| Senior traveler, 70+, pre-existing conditions | Essential (with pre-existing waiver) |
| Budget backpacker, short trip, refundable bookings | Optional (cost may exceed risk) |
Cost Reality Check
What you pay depends mostly on trip length, your age, and the tier you choose.
By Trip Length and Age (Standard Coverage)
| Trip Length | Age 30-40 | Age 50-70 | Age 70+ |
|---|---|---|---|
| 1 week | $40-80 | $80-150 | $120-250+ |
| 2 weeks | $70-120 | — | — |
| 1 month | $120-200 | — | — |
The longer the trip, the less you pay per day.
Age Premium Multipliers
| Age Range | Multiplier vs. Base Rate |
|---|---|
| Age 50-60 | 1.5-2x |
| Age 60-70 | 2-2.5x |
| Age 70-75 | 2.5-3.5x |
| Age 75+ | 3-5x (if coverage available) |
A pre-existing condition waiver adds 20-40% to the premium at any age.
Why Seniors Pay More
Older travelers have higher medical costs, claim more often, and are more likely to have pre-existing conditions. Some providers stop offering coverage at 75-80 years old.
If you're over 70, the same coverage will cost noticeably more. Put that in the trip budget instead of skipping insurance because of the price.
Weighing what insurance costs against what it gives you is a lot like deciding whether a private tour makes sense for your trip. In both cases you pay something up front to cut down on risk and stress.
Premium Add-Ons That Increase Cost
| Add-On | Cost Increase |
|---|---|
| Cancel for any reason | +40-50% |
| Adventure sports coverage | +15-30% |
| Pre-existing condition waiver | +20-40% |
| Higher coverage limits | +30-60% |
Photo credits
- Japanese ambulance with red lights waiting outside an apartment building: Crimage7777 / Wikimedia Commons, CC BY-SA 4.0, resized
- Groomed ski run at Niseko Village with Mount Yotei in the distance: Excellent moniteur de ski / Wikimedia Commons, CC BY-SA 4.0, resized
- Main entrance and tower of St. Luke's International Hospital in Tsukiji, Tokyo: 江戸村のとくぞう / Wikimedia Commons, CC BY-SA 4.0, resized